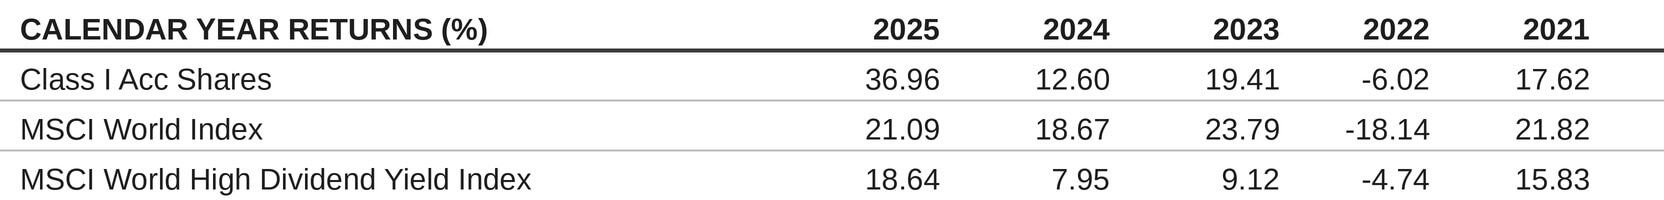
The Equity Income Builder UCITS Fund has generated strong long-term results with less reliance on broad market multiple expansion.
Understanding What Has Driven Global Equity Returns
Global equity markets have delivered strong performance over the past decade. As investors assess current positioning, it is worth examining not only how markets have performed but also what has driven those returns.
A significant portion of global equity returns over this period has come from multiple expansion. The forward P/E of the MSCI World Index has risen from 15.3x ten years ago to approximately 19.1x today, an increase of roughly 25%. While the Magnificent 7 and other U.S. technology companies contributed meaningfully to this trend, the expansion has been relatively broad-based. The equal-weighted MSCI World Index has seen approximately 16% multiple exp
ansion, and even the MSCI EAFE Index has experienced roughly 6% growth in valuations.
Historical P/E – Trailing 10-year
Source: FactSet and Bloomberg
Portfolio attributes can and do vary.
A Different Source of Returns
Despite strong absolute performance in recent years, Equity Income Builder’s relative valuation profile remains attractive, in our view, largely because of how the returns have been generated.
One of the more notable aspects of long-term results has been the limited reliance on valuation expansion. While global equity multiples have moved materially higher over the past decade, the portfolio’s price-to-earnings multiple today is lower than it was ten years ago. This suggests that returns have been driven more by the underlying earnings growth, cash flow generation, and dividend growth of the businesses held, rather than by investors paying higher multiples for those same earnings streams.
Strong Results Without Multiple Expansion
This dynamic is particularly noteworthy given that performance has remained competitive wit
h broader markets over the same period. Despite a lesser contribution from multiple expansion, returns have been broadly in line with the MSCI World Index over the trailing decade and have significantly exceeded those of both the MSCI EAFE and the equal-weighted MSCI World Index.
Annualized Total Return – Trailing 10 Years
A Differentiated Downside Profile
The portfolio’s valuation-sensitive approach and reduced reliance on multiple expansion have also contributed to a differentiated downside experience. Over the trailing 3-, 5-, and 10-year periods, the fund has captured materially less downside relative to the MSCI World Index.
Down Capture Ratio
Equity Income Builder UCITS Fund – Class I Acc Shares vs. MSCI World Index
| 3-Year | 5-Year | 10-Year | |
|---|---|---|---|
| Equity Income Builder UCITS Fund | 34.47% | 56.07% | 72.05% |
Source: Morningstar
Past performance does not guarantee future results.
This reflects a core characteristic of the fund’s investment approach. Rather than pursuing businesses where outcomes depend heavily on continued multiple expansion or increasingly optimistic market expectations, the portfolio emphasizes durable businesses, with consistent cash flow generation, dividend growth, and attractive long-term risk/reward profiles.
By focusing on opportunities where the potential long-term return remains attractive relative to the underlying risks, the fund seeks to maintain a margin of safety while still participating meaningfully in equity market appreciation.
Positioning in Today’s Environment
Investors are right to be thoughtful about capital allocation in the current environment. Following an extended period of strong market performance and significant valuation expansion across portions of the market, uncertainty, both geopolitical and macroeconomic, remains elevated.
Importantly, valuation discipline does not mean avoiding equities altogether. We continue to see attractive opportunities within the portfolio’s investment universe, particularly relative to areas of the market where valuations have expanded most aggressively over recent years. While broader global equity valuations remain elevated relative to history, many of the businesses held within the portfolio continue to offer a differentiated combination of earnings durability, cash flow generation, dividend growth, and more reasonable valuations.
At the individual holdings level, many portfolio companies have experienced multiple expansion over time. However, the portfolio is not static. A key advantage of Equity Income Builder’s flexible, bottom-up approach is the ability to actively reallocate capital, moving from businesses where valuations more fully reflect our assessment of intrinsic value into opportunities where earnings power and cash flow potential remain underappreciated by the market.
This dynamic helps explain how the strategy has generated strong long-term results without relying on the same degree of aggregate multiple expansion seen across global equity markets. A disciplined valuation framework can reduce dependence on continued market re-rating and may better position the portfolio in an environment where fundamentals, cash flow generation, and valuation discipline play a greater role in driving returns.
Discover more about:
More Insights
Signal Over Noise: A Conversation on Global Markets
VettaFi Webcast: The Rise of International Equities
Hyperscalers at the Inflection
Thornburg Income Builder Opportunities Trust Announces Distribution
U.S. Treasury’s New Activism Adds Another Variable for the Dollar and International Equities